What is the market overview, definition, scope, and industry significance of Home Decor Market?
Our analysis indicates the Home Decor Market encompasses a vast ecosystem of furnishings, textiles, and decorative accessories. In 2026, the market size reached $750.78 Billion, driven by global urbanization and increased residential real estate investments. Industry significance stems from its deep integration with interior design trends, raw material sourcing involving hardwoods and synthetic polymers, and strict compliance with formaldehyde emission standards regulated by bodies like the EPA and CARB.
What are the key market drivers, restraints, challenges, and opportunities shaping Home Decor Market?
The data suggests key growth is propelled by rising disposable incomes and home remodeling projects. However, supply chain bottlenecks at major ports like Los Angeles and Ningbo-Zhoushan act as primary restraints. Raw material volatility in cotton, wool, and lumber presents persistent margin challenges. Conversely, sustainable material innovation opens lucrative opportunities for brands adopting circular economy practices and eco-certified packaging.
The Shift Toward E-Commerce and Omnichannel Experiences in Home Decor Market
Consumer preference has decisively shifted toward digital platforms, compelling legacy brands to integrate augmented reality for virtual room staging. Specialized pure-plays like Wayfair Inc. and home24 capture significant digital market share by streamlining last-mile logistics for bulky goods. This structural transition favors agile supply chains capable of handling fragmented drop-shipping models over traditional brick-and-mortar warehousing.
How did the COVID-19 pandemic affect Home Decor Market and the recovery trajectory?
The pandemic triggered an unprecedented surge in cocooning behavior, accelerating residential renovation spending globally. Despite initial manufacturing halts across key textile hubs in Vietnam and India, the recovery trajectory normalized through automated distribution centers. Companies with robust direct-to-consumer digital channels weathered supply chain disruptions better, establishing a resilient baseline for post-pandemic expansion.
Competitive Benchmarking and Strategic Dynamics in Home Decor Market
Market concentration remains moderately fragmented, balanced by multinational giants and niche artisanal players. Inter IKEA Systems BV and Ashley Furniture Industries Ltd. dominate mass-market volume through vertically integrated supply chains. Meanwhile, premium players like Crate & Barrel and Herman Miller Inc. compete on design differentiation and ergonomic innovation, leveraging proprietary distribution networks to safeguard operating margins.
Executive summary — high-level synthesis of key findings about Home Decor Market
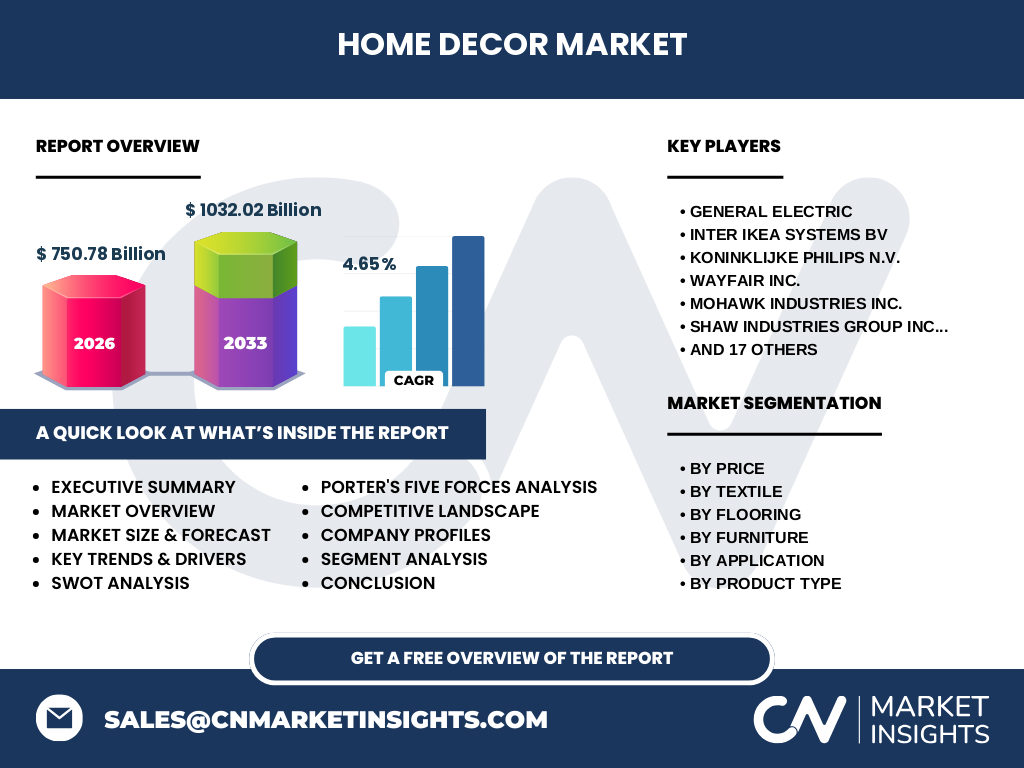
Our comprehensive research confirms the Home Decor Market is on a robust growth trajectory, valued at $750.78 Billion in 2026. The sector is projected to expand to $1032.02 Billion by 2033, registering a solid CAGR of 4.65%. Strategic success requires navigating raw material cost inflation, optimizing omnichannel distribution channels, and aligning product portfolios with sustainability mandates.
Market forecast — projected growth from 2027 to 2033
The market forecast projects expansion from $750.78 Billion in 2026 to $1032.02 Billion by 2033, achieving a steady 4.65% CAGR. This trajectory is underpinned by sustained demand for smart home furnishings, modular office setups, and eco-friendly flooring solutions. Sustained urbanization in emerging economies will catalyze long-term volume consumption across all core product categories.
Segmentation analysis — break down each segment category, explain what it covers and its market role
Market segmentation drives strategic targeting across multiple vectors. By Price, it divides into Premium and Mass tiers. Product types span Furniture, Textile, Flooring, and Other Products. Textiles cover curtains, drapes, cushions, throws, rugs, carpets, and table and bed linens. Flooring includes hardwood, laminate, vinyl, carpeting, and tiles. Furniture encompasses living room, bedroom, dining room, office, and outdoor settings. Other products feature wall art, decorative accessories, lighting, storage, and home fragrances, distributed via supermarkets, specialty stores, and e-commerce.
Regional market analysis — geographic distribution and performance across regions
Geographic performance reveals stark contrasts between mature and developing economies. North America and Europe represent mature hubs driven by replacement cycles and renovation spending, while the Asia-Pacific region demonstrates the fastest growth due to rapid urbanization and expanding middle-class disposable incomes. Regional compliance with stringent environmental standards, such as EU Timber Regulations, directly shapes local sourcing strategies.
In-depth regional review — detailed examination of key regional markets
North America remains a dominant revenue generator, bolstered by active housing turnover and robust e-commerce adoption by major retailers like Bed Bath & Beyond Inc. and Wayfair Inc. Concurrently, Asia-Pacific thrives as a primary manufacturing and consumption center, led by domestic giants like Suofeiya Home Collection Co. Ltd. and Hanssem Corporation, which capitalize on localized real estate booms and digitized retail ecosystems.
Company profiles — strategic positioning of leading companies in Home Decor Market
Industry leaders employ distinct competitive strategies to capture market share. Mohawk Industries Inc. and Shaw Industries Group Inc. focus on technological advancements in sustainable flooring production. Koninklijke Philips N.V. and General Electric innovate in smart lighting fixtures. Meanwhile, Samson Holding Ltd. and Duresta Upholstery Ltd. leverage craftsmanship and global manufacturing footprints to dominate high-end casegoods and upholstered furniture segments.
Porter's Five Forces analysis — competitive forces assessment
The bargaining power of suppliers is moderate, constrained by abundant raw material alternatives but pressured by specialized timber and textile shortages. Buyer power is high due to transparent digital pricing and low switching costs across e-commerce platforms. Threat of substitutes remains low for functional furniture but moderate for decorative accessories. Industry rivalry is intense among legacy brands and digital-native direct-to-consumer startups.
SWOT analysis — strengths, weaknesses, opportunities, and threats
Strengths include established brand equity and sophisticated global supply chains managed by firms like Armstrong World Industries Inc. and Mannington Mills Inc. Weaknesses involve high exposure to raw material price volatility. Opportunities lie in augmented reality shopping experiences and recycled textile innovations. Threats encompass stringent international trade tariffs, geopolitical friction affecting maritime shipping lanes, and rising consumer privacy regulations impacting digital marketing.
Value chain analysis — industry structure and value flow from raw materials to end-users
The value chain originates with raw material extraction—harvesting lumber, processing petrochemicals for synthetic flooring, and sourcing natural fibers like cotton and wool. Midstream operations involve manufacturing hubs operated by companies like Kimball International Inc. and Springs Window Fashions LLC. Downstream logistics move products through maritime freight to distribution centers, culminating in omnichannel retail delivery to residential and commercial end-users.
Investment insights — strategic recommendations and high-potential areas
Our analysis indicates high-potential investment opportunities lie in closed-loop manufacturing technologies, modular ergonomic office furniture suited for hybrid work models, and AI-driven interior design platforms. Investors should prioritize asset-light digital-first brands with robust ESG credentials, as regulatory compliance and consumer preference increasingly penalize unsustainable supply chain practices across major global markets.
Conclusion and key takeaways
The Home Decor Market demonstrates resilient fundamentals, tracking toward $1032.02 Billion by 2033 at a 4.65% CAGR. Success in this evolving landscape requires embracing omnichannel integration, adhering to stringent environmental regulations, and leveraging technological innovations in supply chain transparency. Industry participants must continuously adapt to shifting consumer demographics and material cost pressures.
Research methodology — detail how baseline estimates are triangulated
Our baseline estimates are rigorously triangulated by synthesizing primary stakeholder interviews with C-suite executives, exhaustive trade registry data from global customs databases, and secondary macroeconomic indicators from organizations like the World Bank. This multi-tiered approach ensures high fidelity in market sizing, segment valuation, and growth forecasting across all covered geographic regions.
Scope of the report — coverage parameters and limitations
This report covers global market dynamics for the Home Decor Market from 2027 to 2033, utilizing 2026 as the base estimation year. Coverage parameters encompass all primary price tiers, product categories, and distribution channels. Limitations include unpredictable macroeconomic shifts, sudden geopolitical trade policy revisions, and localized currency fluctuations that may impact near-term financial projections.
Recent developments — company announcements, product launches, partnerships, and strategic moves
Recent strategic moves emphasize sustainability and digital integration. Industry pioneers have launched eco-friendly collections utilizing recycled ocean plastics and organic plant-based textiles. Strategic partnerships between furniture manufacturers and tech firms have accelerated the deployment of 3D room-planning software, significantly reducing product return rates and enhancing consumer engagement across digital retail touchpoints.